


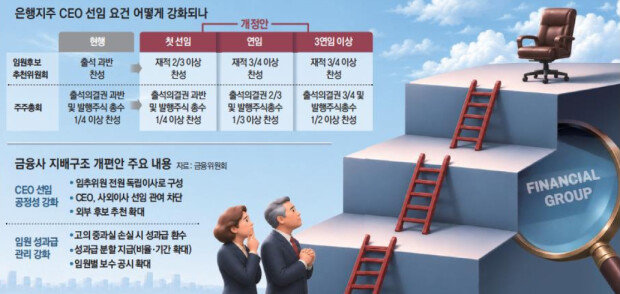
The South Korean government and the ruling Democratic Party of Korea on Nov. 12 unveiled a package of corporate governance reforms designed to make it more difficult for CEOs of financial holding companies to secure consecutive terms and bolster the independence of executive nomination committees. The measures come about 11 months after President Lee Jae-myung denounced what he called a “corrupt inner circle” in the financial industry last December.
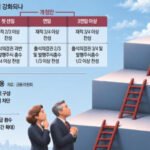
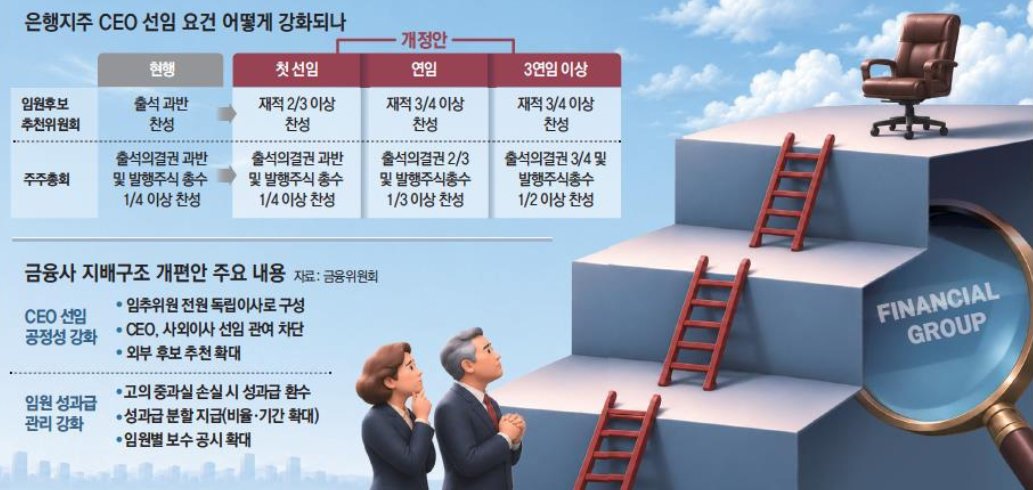
Under the proposals, CEOs of bank holding companies would be appointed by shareholders at general meetings, rather than by boards of directors. The thresholds for nomination committees to approve CEO candidates would also rise substantially. A simple majority is currently sufficient, but the proposed rules would require a two-thirds majority for an initial appointment and a three-quarters majority for reappointment. Rather than impose term limits, which could invite constitutional challenges, the government has chosen to make securing another term considerably more difficult. Nomination committees would also be composed entirely of independent outside directors with no ties to incumbent CEOs. On a seven-member committee, just two votes against a candidate would be enough to block a reappointment.
Stronger checks on executive power are warranted at financial institutions, which, like other companies without controlling shareholders, lack a dominant owner capable of counterbalancing an incumbent CEO’s influence. Regulators have uncovered instances of self-serving succession practices and executive entrenchment at financial holding companies. In some cases, companies raised the age limit for executives after succession procedures were already underway, allowing sitting chairmen to seek another term. In others, individuals close to the chairman were permitted to participate in the succession process.
The danger, however, is that regulators could use these abuses to establish yet another precedent for government-directed finance by weakening the authority of financial company boards and imposing cumbersome succession procedures. Under current law, CEO succession is subject to deliberation and approval by the board. The proposed revisions, however, would strip boards of that authority and transfer the appointment decision to shareholder meetings. They would also require the support of at least 75 percent of shareholders for a CEO’s second consecutive reappointment, effectively giving shareholders holding just 25 percent of the shares the power to block a decision backed by the majority.
Regulators have also proposed allowing institutional investors, including the National Pension Service, to nominate independent directors to take part in succession planning. Unless their independence is firmly safeguarded, such an arrangement could give the government a foothold in the governance of financial institutions and pave the way for politically connected appointments. To prevent another controversy over government-directed finance, robust safeguards are needed to monitor and forestall informal government interference.
Jamie Dimon has led JPMorgan Chase, the largest U.S. bank, since 2006, a tenure approaching two decades. The objective of corporate governance reform should not be to penalize CEOs for serving long terms. Rather, it should be to empower independent, accountable boards to check excessive executive power. The lines of responsibility must be clearly drawn. The choice of leadership belongs to boards and shareholders, while regulators should focus on ensuring accountability.