

 |
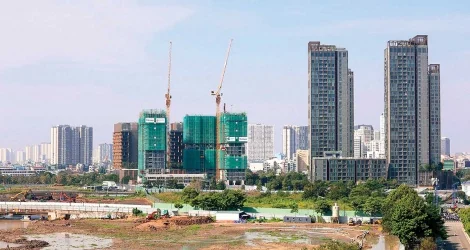
| Empire City project in Thu Thiem |
When the value of an asset is no longer determined by the size of its land holdings.
After years of stagnation due to legal issues, the Lotte Eco Smart City project in the Thu Thiem New Urban Area (Ho Chi Minh City) is being restarted with the participation of a domestic partner.
Accordingly, Phat Dat Real Estate Development Joint Stock Company will participate with a 35% ownership stake, co-developing the residential component in lots 2-2, 2-4, and 2-6. In the commercial-service and office component, Phat Dat will undertake the development of the entire two high-rise blocks 2-1 and 2-3. The total investment capital of the project has also been adjusted from over 20,100 billion VND to approximately 60,000 billion VND.
Lotte Eco Smart City is a large-scale, multi-functional urban complex integrating Grade A office towers, commercial and retail podiums, services, accommodation, housing, and public spaces within a single, integrated ecosystem, adhering to international standards for urban planning, development, and operation.
 According to Grant Thornton, in September 2026, the Vietnamese M&A market recorded 30 announced transactions. Of these, 23 deals had an announced or estimated value totaling approximately US$1.74 billion. Notably, restructuring and related-party transactions contributed approximately US$1.23 billion, equivalent to 70.7% of the total transaction value. The VinFast deal to acquire 100% of Ngoc Hoi Real Estate Investment Joint Stock Company alone was valued at approximately US$1.2 billion.

However, the journey to the groundbreaking ceremony was not entirely smooth. The project faced numerous challenges, particularly legal obstacles that prolonged the preparation process.
In particular, the realization of the joint venture model between Lotte Group and its domestic partner has created an important foundation for the project to officially commence construction. This model combines the financial capacity and international operational experience of the Korean group with the market understanding and legal enforcement capabilities of Vietnamese businesses.
In reality, given the high cost of capital, lengthy project development times, and increasingly stringent legal requirements, owning large land reserves may not necessarily provide an advantage if the business lacks the resources to implement the project.
According to Ms. Cao Thi Thanh Huong, Deputy Director of Research and Consulting at Savills Ho Chi Minh City, asset transfer is becoming a solution to help businesses shorten their capital turnover cycle.
Through transactions, businesses can recover a portion of their invested resources, reduce the need for financial leverage, and reallocate capital to projects with more complete legal frameworks, faster implementation potential, or those that better match market purchasing power.
From this perspective, M&A is not just about buying and selling land between investors, but also becomes a tool for restructuring capital and reselecting projects that have the potential to create real value.
The shift is also reflected in the strategies of international investors, as directly owning real estate is no longer the only option to enter the market. Keppel Group ( Singapore ) plans to transfer its entire 40% stake in Empire City Joint Venture Company Limited, the developer of the Empire City project in Thu Thiem, for a value of US$270 million.
It’s worth noting that withdrawing capital from a project doesn’t necessarily mean the investor underestimates market prospects. According to Keppel, the divestment is part of a portfolio restructuring strategy, moving towards a model of asset management and operation rather than directly holding real estate projects.
Lee Kok Chew, Head of Divestment Acceleration at Keppel, said the transaction is expected to bring in approximately S$343 million in cash this year, reflecting Keppel’s consistent efforts to unlock value from non-core assets and further its strategy of becoming a global asset manager and operator with a lightweight asset model.
Another example of this trend is the acquisition of Serenity Holding, the owner and operator of Fusion Hotel Group in Vietnam, by the founder of SC Capital Partners.
Following the transaction, Fusion will be integrated with HMJ (Japan) and Topotels ( Indonesia ) to manage approximately 16,000 hotel rooms across four high-growth Asian markets, supported by a team of over 100 hospitality professionals. In this deal, the value sought by the buyer lies not only in the property portfolio but also in the Fusion brand, its management system, its customer network, and the potential for synergy across multiple markets.
This shows that real estate M&A is increasingly linked to the challenge of creating value after the transaction. A deal is only truly effective when the investor can improve its operational capacity, expand its market, or create synergy between the assets in its portfolio.
Selective capital flows, valuation based on actual performance.
These developments are taking place against a backdrop where M&A activity continues to see large-scale transactions, but capital flows are no longer evenly distributed across asset classes.
According to Grant Thornton, in September 2026, the Vietnamese M&A market recorded 30 announced transactions. Of these, 23 deals had an announced or estimated value totaling approximately US$1.74 billion. Notably, restructuring and related-party transactions contributed approximately US$1.23 billion, equivalent to 70.7% of the total transaction value. The VinFast deal to acquire 100% of Ngoc Hoi Real Estate Investment Joint Stock Company alone was valued at approximately US$1.2 billion.
Mr. Ta My Bach, Director of Capital Markets at JLL Vietnam, stated that the market is witnessing a clear shift from investment strategies based on price appreciation expectations to investment strategies based on asset quality and actual operational efficiency.
According to him, in an environment where capital costs remain high, investors are increasingly prioritizing projects that can generate stable cash flow, possess long-term competitive advantages, and meet sustainable development standards. These will be the decisive factors in the market’s ability to attract capital in the next phase.
This shift directly impacts how real estate is valued in M&A transactions. Previously, large land holdings, prime locations, or expectations of infrastructure development could be important factors for investors to accept high valuations. Now, those factors are still valuable, but insufficient if the project lacks clear legal status, has an uncertain implementation timeline, or struggles to demonstrate revenue generation potential.
For commercial real estate, offices, and hotels, investors are more interested in occupancy rates, tenant retention potential, operating costs, and the cash flow that can be generated after the transaction. For residential projects, the progress of legal procedures, product development potential, actual purchasing power, and payback period become important variables in the appraisal process.
“Capital flows are concentrating on projects with high transparency, strategic locations, good infrastructure connectivity, and developed by reputable investors,” Mr. Bach noted , adding that the appraisal process is becoming increasingly stringent as investors prioritize capital preservation over speculative price appreciation opportunities. The focus of evaluation has now shifted to asset quality, the ability to generate stable cash flow, and sustainable long-term operational efficiency.
According to Mr. Bach, the biggest obstacle in the market today is not necessarily liquidity or investor interest, but mainly the gap in expectations between buyers and sellers. While many owners expect selling prices to reflect the market’s recovery prospects, international investment funds are more cautious after a period of significant global economic volatility.
This gap is not just a difference in price, but also shows that the seller focuses on the value already invested and future potential, while the buyer must calculate the cost of capital, legal risks, implementation time, and potential profit.
Sharing the same view, Ms. Cao Thi Thanh Huong believes that investors are prioritizing assets with transparent legal status, favorable locations, good infrastructure connections, and developed by reputable developers. Instead of placing high expectations on price appreciation, capital flows are focusing more on the ability to preserve capital, generate stable cash flow, and maintain long-term operational efficiency.
According to JLL’s assessment, future real estate M&A activity is expected to continue focusing on quality assets in the residential, resort, data center, and select commercial real estate segments.
However, the transaction outlook will depend on the ability to narrow the valuation gap between buyers and sellers, along with resolving legal issues and improving asset quality. “We expect this gap to gradually narrow as market confidence improves and successful deals continue to be recorded in the coming period,” Mr. Ta My Bach commented.