
Private equity investors have shown interest in various industry sectors, ranging from restaurant chains to New York City residential buildings—and financial service firms also have an allure.
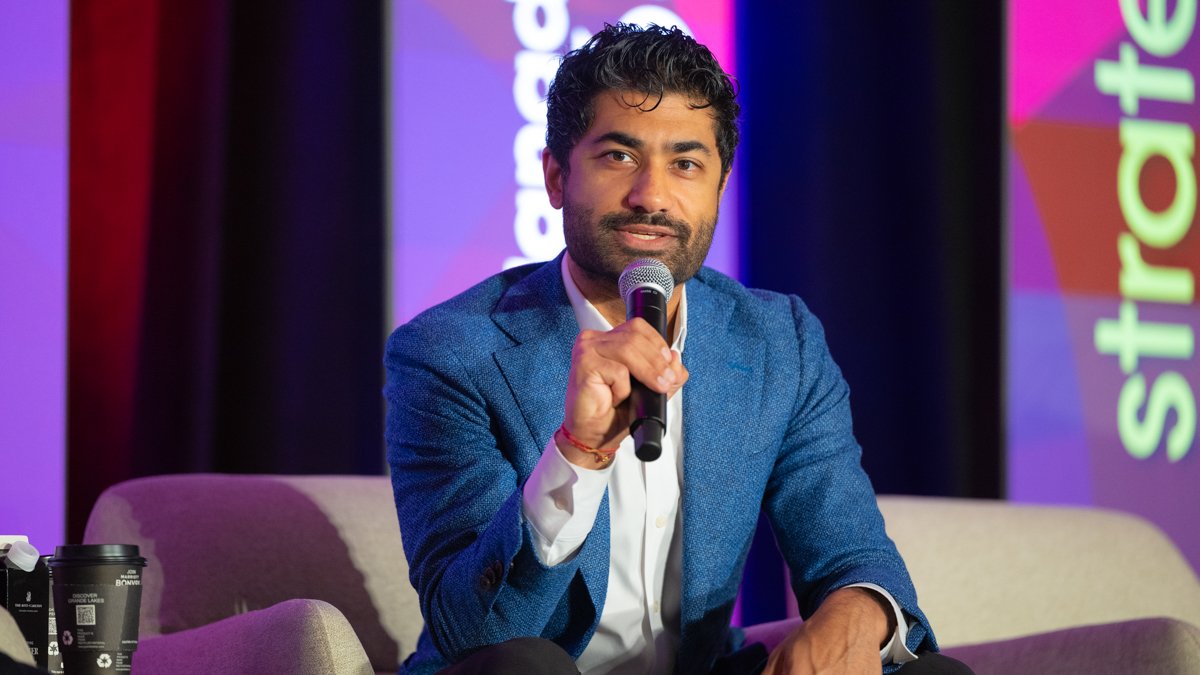
Vidur Khatri, a principal at Abry Partners, a Boston-based private equity firm, shared his perspective Tuesday morning at the 2026 PLANADVISER 360 Conference in Orlando, Florida. In “Understanding Private Equity’s Interest in Advisory Firms,” Khatri said his firm focuses on the financial service sector.
“I spend most of my time … within law [practice] management, insurance services, retirement services [and] accountancies,” he said. “We come in to potentially partner with firms to either provide a solution, or capital to continue to grow the business. … We partner with companies, from anywhere between three to five to seven years.”
Khatri said, in private equity, the partnership is meant to elevate the client relationships that firms already have in place.
“It’s really about never losing that client-adviser relationship,” he said.
Green Flags—and Red Flags—for PE Buyers
Khatri noted some “green flags” that advisory firms could highlight, and red ones they might want to hide, to attract a potential private equity partnership.
First, Khatri said, he looks for clarity in relation to a firm’s succession strategy.
“It is very clear when you walk into a room and a business is for sale how well they’ve been prepared for sale,” he said.
Firms with identified second- and third-generation leadership teams tend to be more attractive investment opportunities because they demonstrate continuity beyond the founder, Khatri said.
He also pointed to durable client relationships; specialized expertise; and multiple avenues for growth, including technology investments, recruiting, and merger-and-acquisition dealmaking. “We love to come in and invest in businesses where there [are] multiple levers for growth—[where businesses are] continuing to invest in technology, continuing to recruit amazing talent to service clients better, and selectively look[ing] at M&A,” Khatri said. “M&A really grows the value of the business—makes it a better business versus just making it [a] bigger business.”
Another form of growth that can come with M&A, according to Khatri, is a firm’s ongoing focus on the convergence of retirement and wealth planning. As an example, he pointed to the time, three years ago, when his firm invested in Prime Capital Financial, a Kansas-based registered investment advisory that had a retirement and wealth planning practice.
He said Prime Capital showed a continued focus on investing more than just on increasing services such as wealth planning. He said Prime Capital was a fully integrated financial services firm with a well-thought-out wealth and retirement arm.
“The idea that retired advisory and wealth can converge … there is trust built with employers in such an important [combined] service,” Khatri said. “You can turn those assets into managed assets through either managed paths or wealth management services.”
In contrast, Khatri said, red flags pop up for firms heavily dependent on a single leader, or lacking a succession plan, or those whose growth strategies rely solely on acquisitions.
“We think M&A, when done right, creates a lot of value,” he said. “But just buying businesses for the sake of accumulation can get sideways really fast.”
What Advisers Should Be Asking
Beyond evaluating a firm’s readiness for investment, Khatri encouraged advisers considering private equity partnerships to question potential investors as carefully as investors evaluate them.
He highlighted that private equity always has a beginning date and an end date to its investment. Because thousands of private equity firms operate in the market, he said, advisers should focus on finding partners whose expertise, investment timeline and growth strategy align with their own objectives.
“In the beginning, [private equity is] going to invest a lot of capital. Hopefully, by the end, they’re going to take out a lot of capital,” Khatri said. “So aligning on what that three-year plan [or] five-year plan looks like and what you make [on] those investments is critically important.”
Questions advisers should ask include how the investor responds when portfolio companies face challenges, what resources it can provide beyond capital, and whether current or former portfolio company executives would recommend working with the firm.
“Ask, ‘Well, what are you going to do for me?’” Khatri said. “‘What are you bringing to the table?’ ‘How do you work when something doesn’t go right?’ ‘Can I speak to a CEO that you worked with before, when things didn’t go as expected?’ Those are the best questions to ask before taking on a private equity investment.”
After the Deal
Khatri said some of Abry’s most successful investments in financial services have been minority stakes rather than controlling acquisitions.
“These deals are where we do not actually own more than 51% of the business. … There is just really good alignment when you own less of the business,” he said.
According to Khatri, founders who retain a minority ownership stake often are still significantly invested in the firm’s growth, creating stronger alignment between management and investors.
He added that the due diligence process is designed to identify legal, financial and operational risks while helping both parties determine whether they are the right long-term fit.
“There is a pre-diligence process, [which] is a vetting process. … If the private equity firm is coming in, if we are investing, … what sort of changes do we want to make? Or what do we want to keep the same? And often, it’s keeping things the same and it’s just adding value around the margins,” Khatri said.
“The diligence process is the process in which you look to uncover any kind of pitfalls of the investment, the asset itself,” he said. “Look for weak areas, legal points, financial points.”

Leave a Reply