Summary: In Mexico, the highest regional B2C sales are driven by localized social media and live-shopping campaigns in lower-CAC secondary corridors—such as Queretaro, Guanajuato, Puebla, the State of Mexico, and Chihuahua—paired with Buy Now, Pay Later (BNPL), digital wallets, and hybrid cash-voucher options that overcome credit card distrust. Conversely, peak regional B2B sales rely on relational WhatsApp conversational commerce integrated with ERP/CRM systems, settled through real-time SPEI account-to-account transfers and automated foreign exchange hedging tools that eliminate transaction friction across SME and nearshoring supply chains.
Commercial growth in Mexico is increasingly defined by how effectively enterprises adapt their customer acquisition strategies and checkout infrastructure to regional realities. While Greater Mexico City, Guadalajara, and Monterrey historically absorbed the lion’s share of corporate marketing budgets, rising digital advertising costs and congested urban logistics have pushed high-growth companies toward secondary industrial and consumer corridors.
Across both business-to-consumer (B2C) and business-to-business (B2B) segments, the highest regional sales performance now belongs to organizations that pair hyperlocal, conversational engagement with payment rails tailored to Mexican financial habits.
In the B2C arena, brands are capturing superior return on investment by shifting promotional spend into provincial hubs such as Queretaro, Guanajuato, Puebla, the State of Mexico, and Chihuahua. In Unlocking Faster E-Commerce ROI in Mexico’s Secondary Corridors, regional consumers exhibit rapidly rising digital adoption while facing far less advertising saturation than shoppers in Tier-1 metropolises, resulting in lower customer acquisition costs and faster marketing payback windows.
Rather than relying on generic national display ads, winning retailers localize discovery through social media, influencer recommendations, and interactive live shopping. Data published in Social Media Drives 65% of Mexico Consumer Purchases: Kueski reveals that 65% of Mexican consumers have bought products after encountering recommendations on social platforms.
In The 5 Engines Redefining the Power of E-Commerce in Latin America, Hector Tinjacá, General Manager North LATAM at VTEX, underscores this structural shift in how regional demand converts.
“The social feed has definitively become a new point of sale (POS). With the rise of Live Shopping and native interaction systems, the traditional funnel has been reconfigured, and conversation is the sale, which demonstrates that immediacy becomes a decisive factor.”
However, localized B2C marketing only translates into completed regional revenue when checkout options remove financial friction and distrust. Across much of Mexico, traditional credit card penetration remains uneven, and many shoppers hesitate to share sensitive banking credentials online.
As detailed in BNPL: Reshaping Consumer Behavior and Financial Habits in Mexico, Buy Now, Pay Later (BNPL) platforms such as Kueski and Aplazo have become decisive conversion catalysts by offering transparent, short-term, interest-free installments without requiring a traditional bank card; notably, 63% of surveyed BNPL users reported they would not have completed their purchase without a pay-later option. At the same time, merchants must accommodate diverse regional payment preferences across the digital-to-physical spectrum.
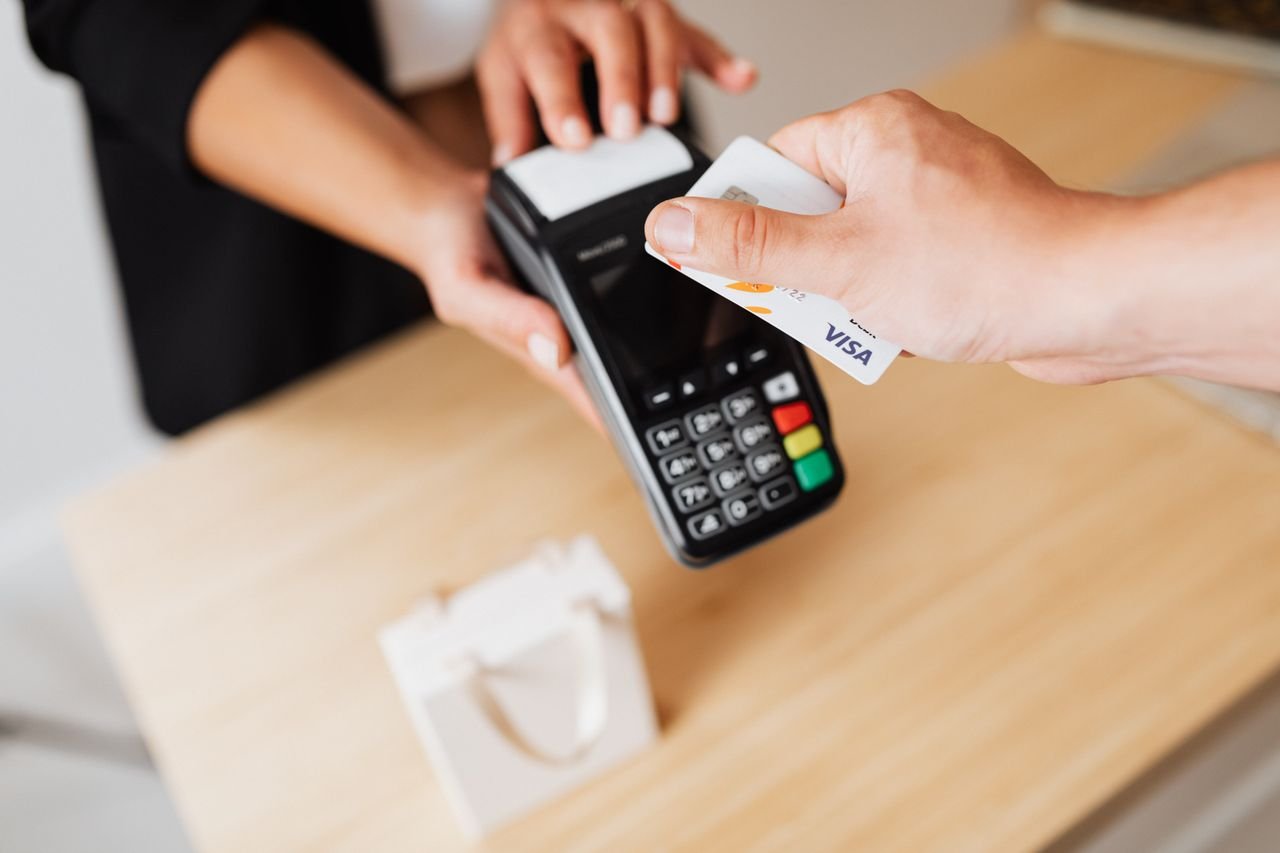
While Mexico Shifts Toward Digital Payments in Retail, E-Commerce notes that point-of-sale cash reliance is projected to decline from 40% to 35% by 2030, Cash, SPEI, Credit Cards: What Do Mexicans Actually Want? and Mexico and E-Commerce: Opportunities and Gaps in the Digital Boom emphasize that combining digital wallets, instant bank transfers, and cash-voucher bridges like OXXO Pay remains essential to serve both banked urban buyers and cash-reliant provincial households.
On the B2B side, regional sales success follows a distinct relational and operational blueprint. Unlike the United States or Western Europe, where enterprise procurement migrated toward formal asynchronous portals, Mexican B2B commerce is anchored by small and medium-sized enterprises across auto parts, agribusiness, consumer goods distribution, and industrial supplies that conduct business directly through messaging apps.
As outlined in The Untapped B2B Conversational Commerce Gap No One Talks, WhatsApp functions as Mexico’s de facto commercial backbone for supplier quotes, contract negotiations, and recurring reorders. Yet top-performing B2B distributors differentiate themselves by moving beyond disconnected sales chats and embedding WhatsApp directly into enterprise resource planning (ERP) and customer relationship management (CRM) workflows.
In that same Expert Contributor piece, Sergio Acevedo, CEO of Concepto Móvil, highlights the strategic shift required to capture regional B2B volume.
“Mexican B2B leaders need to stop asking, ‘How do we sell through WhatsApp?,’ and start asking, ‘What does account infrastructure look like when every customer interaction lives in one place?'”
Once a regional B2B order is initiated via conversational channels, payment speed, low transaction fees, and currency stability determine whether deals close profitably. Banco de México’s Interbank Electronic Payment System (SPEI) has emerged as the premier B2B settlement rail, clearing billions of real-time account-to-account transfers annually without the high interchange fees or ticket limits associated with corporate cards.
According to Cobre Clears $1.5 Billion Monthly in Mexico as B2B Payments Surge, corporate adoption of SPEI-integrated treasury platforms alongside automated foreign exchange protection has accelerated sharply among nearshoring manufacturers, logistics operators, and regional wholesalers managing peso-dollar volatility. Referring to the 25-fold growth of Cobre’s Rate Lock currency hedging solution, José Gedeón, CEO and co-founder of Cobre, explains how localized financial tooling unlocks commercial resilience.
“This is the result of designing a tool that reduces friction and complexity in exchange rate protection, allowing companies to take preventive action in an environment of controlled yet constant volatility.”
Ultimately, unifying localized marketing with multi-rail payment orchestration is what separates market leaders from laggards across Mexico’s regions. As reported in Aggregators Shift Acquiring Networks to Win Mexico Retail, modern payment processors that integrate cards, SPEI, Banco de México’s DiMo mobile transfer framework, conversational payment links, and machine-learning fraud routing have lifted merchant approval rates from historical baselines of 50% to above 75%.
Whether converting a first-time social shopper in Puebla through BNPL or automating a recurring SPEI-settled supply reorder over WhatsApp in Chihuahua, businesses achieve their highest regional sales when every local touchpoint leads seamlessly to a trusted, frictionless payment.