Warnings have emerged that if the bill to introduce a mandatory tender offer system, currently pending in South Korea’s National Assembly, passes in its original form, foreign capital outflows could expand and push the KOSPI down to the 3,900 level. Critics argue that a system billed as protecting ordinary shareholders could instead entrench a structure that concentrates control premiums in the hands of controlling shareholders, deepening the “Korea discount.”
The Korea Corporate Governance Forum (chaired by Lee Nam-woo) issued a commentary on the 17th, stating: “If the Capital Markets Act amendment currently pending in the National Assembly passes the plenary session without revision, large-scale foreign selling will send share prices plunging.” The forum said “the decline could reach the KOSPI’s 4,200 level—equivalent to a price-to-book ratio (PBR) of 1x—and, if supply-demand imbalances worsen, even 3,900.” It thus presented a PBR of 1x as the 4,200 level and roughly 0.93x as the 3,900 level.
The forum cited as background a combination of weakening expectations for the semiconductor cycle and damaged trust in the government’s commitment to capital market reform. It explained that if shareholder protection retreats at a time when earnings growth expectations are already low, the discount factor applied to South Korean companies will widen again. It added that if long-term foreign investors come to doubt the level of shareholder rights protection in the South Korean market and reduce their allocations or raise their discount rates, selling pressure could intensify.
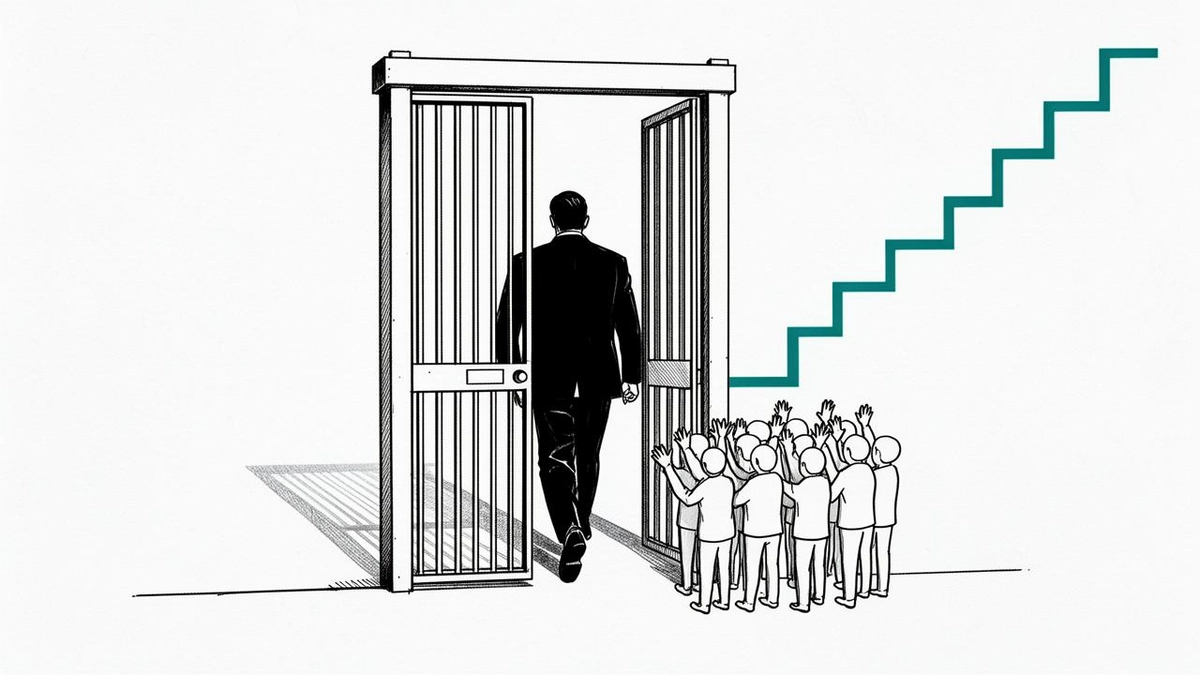
The crux of the dispute is how many shares ordinary shareholders can sell at the same price in a change-of-control transaction. Under the amendment, once an acquirer secures at least 25% of shares and becomes the largest shareholder, it must acquire a majority of all shares, including those it already holds, while being allowed to buy the controlling shareholder’s stake first—a so-called “preceding purchase.” If the existing major shareholder holds 40%, the tender offer volume directed at ordinary shareholders amounts to only about 10% of the total. Even if all remaining shareholders tender their shares, each would be able to sell only about one-sixth of their holdings.
Overseas institutional investors are also raising the issue. The Asian Corporate Governance Association (ACGA) and the International Corporate Governance Network (ICGN) recently sent letters to South Korea’s National Assembly and financial authorities, urging that controlling and ordinary shareholders be guaranteed equal opportunities to sell. The ICGN proposed that even if the majority-purchase principle is retained, all shareholders should participate in the tender offer together and sell in proportion to the shares they tender. The forum said these organizations conveyed the position that the “50% plus one share” threshold and the preceding-purchase method conflict with the principle of shareholder equality and the intent of the amended Commercial Act.
The sale of control of Aekyung Industrial is cited as a representative case in which ordinary shareholders were sidelined. Taekwang Group and Aekyung Group agreed in February to a negotiated acquisition price of 26,642 won (approximately $20) per share, 77% above the market price at the time. Ordinary shareholders did not get the opportunity to sell their stakes at the same price, and the stock rose to 19,100 won (approximately $14) in February before falling to around 10,000 won (approximately $7.5) recently.
By contrast, the forum emphasized that overseas markets give ordinary shareholders the same opportunity. When Samsung Electronics acquired U.S.-based HARMAN in 2016, all shareholders received the same price and control premium, and when Samsung Biologics acquired Switzerland’s PolyPeptide Group, the same tender offer price applied to both controlling and ordinary shareholders, according to the forum.
The forum also rebutted the private equity industry’s claim that a 100% mandatory tender offer system would shrink the M&A market. In the industry’s view, large-scale deals remain entirely feasible using acquisition financing and co-investors. It added that M&A is active in advanced economies such as the United States even as they guarantee ordinary shareholders a fair opportunity to sell.
Lee Nam-woo, the forum’s chairman, said: “What the National Assembly must protect is not the privileges of a handful of controlling shareholders and private equity funds, but the property rights of the public.” He added: “We must mandate a tender offer for all remaining shares and move quickly to introduce a ‘bear hug’ that allows a takeover to be publicly proposed without management’s consent.” The forum argued that a 100% mandatory tender offer system conforms to global standards that protect the property rights of virtually the entire population, including 14.4 million individual investors and beneficiaries of the National Pension Service.
The debate remains unresolved even within the ruling party. South Korea’s Democratic Party of Korea discussed the related agenda at a policy meeting on the 10th but reportedly failed to reach a consensus. A public petition demanding revisions to the bill surpassed 50,000 signatures in just six days. South Korean President Lee Jae-myung attempted to spark public debate on October 28 via X, asking: “What is a reasonable balance point that substantially protects minority shareholders’ rights while not sapping the momentum of the corporate acquisition market?”
The effectiveness of the bill has also come under scrutiny. The average stake of major shareholders in South Korean listed companies is around 44%, meaning that under the National Assembly’s version, there are many cases in which an acquirer would not need to buy ordinary shareholders’ stakes at all. If the controlling shareholder already holds a majority, the acquirer has no need to make a tender offer to ordinary shareholders in the first place. Critics also note that a controlling stake could be raised above 50% through share buybacks and cancellation, after which the stake could be transferred—avoiding the tender offer obligation altogether.
Conversely, concerns that mandating a full buyout would sharply increase acquisition costs also face strong counterarguments. Analysts say the actual burden would not rise much because the control premium paid to major shareholders could be lowered. European countries such as the United Kingdom and Germany mandate the purchase of all remaining shares, and in the United States, voluntary full buyouts are common even without such a rule. South Korean research also indicates that after such a system was introduced, control premiums were rationalized from 60% to 23%, easing the acquirer’s burden.
Stock market experts see the fate of the bill as a significant variable for foreign fund flows. They expect that if legislation retreating from the principle of shareholder equality is finalized, it could lead global institutions to adjust their discount rates for the South Korean market, potentially putting the brakes on the KOSPI’s valuation recovery.