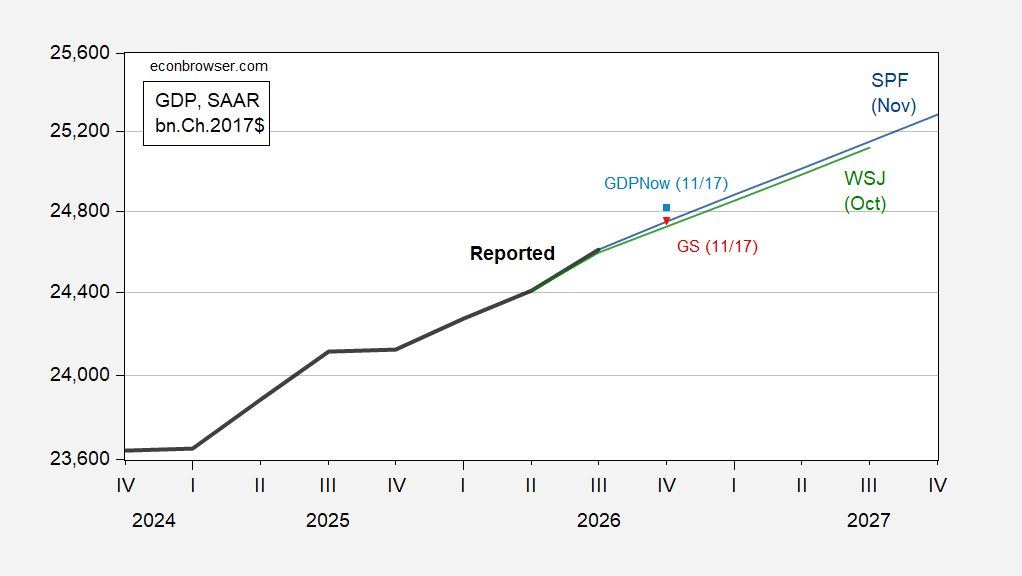
Continued growth, low probability of negative growth. From the Survey:
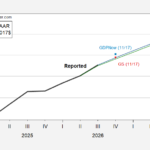
Figure 1: GDP, advance release (bold black), November SPF median (blue), October WSJ survey mean (green), GDPNow (light blue square), Goldman Sachs (inverted red triangle), all in bn.Ch.2017$ SAAR. Levels calculated by iterating growth rates on latest reported relevant GDP level, except for SPF. Source: BEA 2026Q3 advance, Philadelphia Fed, WSJ, Atlanta Fed, Goldman Sachs, and author’s calculations.
NABE also released the results of their survey (but it’s behind a paywall), with median 2026 GDP growth q4/q4 at 2.4%, below SPF median 2.6%. Here’s a summary:
“Panelists have raised their 2026 and 2027 forecasts for both business investment and growth, and have lowered their job growth forecasts for 2026 and 2027 while expecting the unemployment rate to hold near 4.2%. Energy remains the main source of inflation pressure, and the panel raised its oil price forecasts for both years. Productivity forecasts edged lower, yet nearly half of panelists now cite stronger productivity growth as the greatest upside risk, overtaking an end to the wars in Ukraine and the Middle East. On the downside, broadening geopolitical conflicts regained ground as the top risk, and half of the panel sees risks tilted to the downside. Even so, confidence that a downturn is not imminent held: recession odds are little changed, and more than half of panelists do not expect the next recession to begin before 2029.”