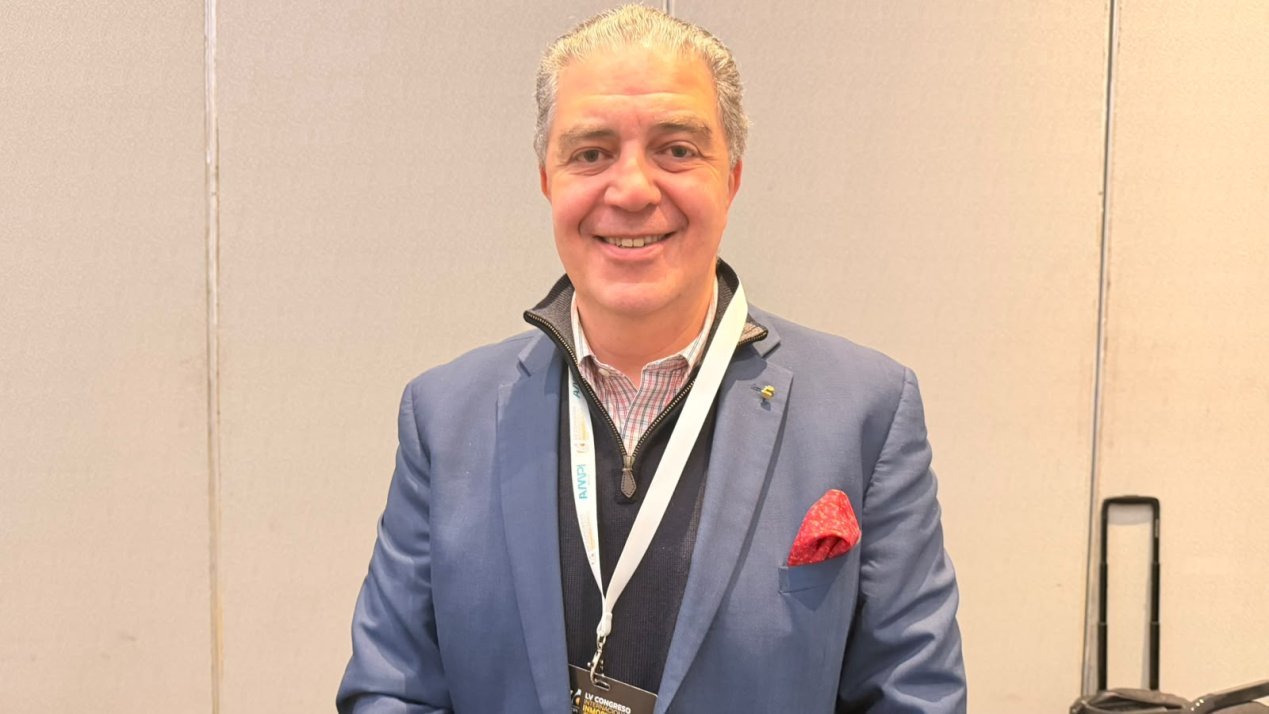
Nearshoring has transformed Mexico’s industrial real estate market, but trade uncertainty, electricity distribution constraints, and water availability are creating new obstacles for investment. During the AMPI International Real Estate Congress 2026, José Antonio Hagg discussed the infrastructure challenges that could shape Mexico’s industrial competitiveness through 2030.
Mexico’s industrial infrastructure sector is undergoing a transformation driven by nearshoring, trade uncertainty, and the increasingly sophisticated technological requirements of manufacturing and logistics operations. Although the relocation of production activities has stimulated demand for industrial parks, warehouses, and distribution facilities, the market now faces a more complex environment in which investment decisions depend heavily on electricity availability, water resources, and infrastructure capable of supporting automated industrial processes. These challenges were addressed by José Antonio Hagg Hagg, a corporate real estate and portfolio strategy specialist with more than 15 years of experience managing multinational property portfolios across Latin America, during an interview at the 55th International Real Estate Congress organized by the Mexican Association of Real Estate Professionals (AMPI).
Hagg explained that nearshoring initially generated a surge in demand for industrial properties that exceeded existing supply, encouraging developers to expand capacity and launch new projects. However, this dynamic began to change as tariffs and trade uncertainty affected expansion plans, altering the balance between industrial construction and occupancy. According to Hagg, the market has experienced fluctuations between periods of exceptionally strong demand and stages in which newly developed properties have increased availability beyond initial expectations.
To illustrate this changing environment, Hagg described nearshoring and tariffs as opposing forces influencing industrial development. While nearshoring accelerated demand for manufacturing and logistics facilities, tariffs introduced uncertainty that slowed investment decisions. This interaction has created a market characterized by shifting supply and demand conditions, requiring developers, investors, and industrial operators to reassess expansion strategies and carefully evaluate the timing of new projects.
One example highlighted during the interview was Tijuana, where Hagg observed an increase in industrial property availability compared with earlier expectations. He attributed part of this development to the slowdown in demand associated with tariffs and uncertainty surrounding cross-border trade. The situation illustrates how US trade policies can influence industrial infrastructure planning in Mexico, particularly in border regions closely integrated into North American manufacturing and supply chains.
Trade uncertainty has also complicated project planning and investment decisions. Hagg argued that tariffs and the broader uncertainty surrounding US-Mexico commercial relations have significantly weakened industrial demand. Nevertheless, he characterized these developments as part of economic and political cycles that may eventually stabilize, allowing companies to resume expansion plans and generating renewed demand for industrial properties.
From his perspective, Mexico continues to maintain structural advantages over competing markets because of its geographic proximity to the United States and the extensive border shared by the two countries. Hagg emphasized that these characteristics remain relevant for companies seeking to operate near the US market, even when tariffs create additional costs or uncertainty. However, he acknowledged that the timing of a potential recovery remains difficult to predict, particularly while companies evaluate the implications of evolving trade policies.
Beyond commercial uncertainty, Hagg identified a significant transformation in the infrastructure requirements of industrial property users. Logistics facilities that once required relatively modest electrical capacity are increasingly incorporating robotics, automated equipment, and advanced technologies that substantially increase electricity consumption. This evolution is changing the criteria used to design, construct, and modernize warehouses and distribution centers.
Hagg emphasized that modern logistics operations can no longer be evaluated solely according to available floor space, location, or traditional warehouse specifications. The introduction of robotics and automated systems requires electrical infrastructure capable of supporting continuous operations and increasingly complex technological processes. Consequently, power availability has become a determining factor in assessing the feasibility of new industrial developments and upgrading existing facilities.
These changes also reflect the broader transformation of supply chains. As companies seek greater operational efficiency, logistics properties must accommodate technologies that require additional energy capacity and more sophisticated infrastructure. For developers, this means that projects originally designed for conventional storage and distribution activities may need substantial adaptations to meet the requirements of automated operations. The ability to provide sufficient electrical capacity could therefore become an increasingly important competitive advantage for industrial real estate assets.
Artificial intelligence is introducing another layer of infrastructure demand. Hagg noted that although the expansion of AI-related facilities is not directly attributable to nearshoring, it forms part of the technological evolution influencing industrial property requirements. Facilities supporting these operations may occupy comparatively limited physical space, but their electricity and water requirements can be substantial.
This development creates additional pressure on resources in regions where industrial activity is already expanding. The simultaneous growth of logistics automation, manufacturing operations, and AI-related infrastructure could intensify competition for electricity and water, making resource availability an increasingly important factor in site selection. For companies evaluating future investments, access to utilities may carry as much weight as transportation connectivity or proximity to customers.
When asked about the principal infrastructure bottlenecks limiting Mexico’s industrial expansion toward 2030, Hagg identified two priorities: water and electricity. He emphasized that water availability is becoming an increasingly significant constraint, while the electricity sector faces challenges that require distinguishing between power generation and the infrastructure needed to deliver electricity to industrial consumers.
According to Hagg, one of the most important obstacles is not necessarily the country’s ability to generate electricity, but the limitations of its distribution networks. He explained that expanding electricity distribution infrastructure can require between two and three years, making early planning essential to ensuring that industrial parks and other economic centers can access sufficient power when demand increases.
This distinction between electricity generation and distribution is critical for industrial infrastructure planning. A project may have suitable land, transportation connections, and potential tenants, but still face operational delays if the surrounding electrical network cannot support its requirements. From this perspective, coordination among developers, public authorities, and electricity infrastructure operators becomes essential to preventing distribution constraints from delaying industrial investment.
Hagg urged authorities to accelerate the development of electricity distribution infrastructure, emphasizing that the time required to complete these projects means investment decisions must be made well before additional capacity is needed. His assessment suggests that infrastructure planning undertaken today will directly influence Mexico’s ability to accommodate future industrial expansion, particularly if demand recovers following the current period of trade uncertainty.
The challenges identified during the interview also have important implications for industrial real estate developers. Expansion strategies must increasingly consider not only projected occupancy and market demand but also whether specific regions can provide the essential services required by industrial users. In a market where automation is raising electricity consumption and water availability is becoming a determining factor for certain activities, supporting infrastructure can be as important as the construction of new buildings.
These conditions may also influence the modernization of existing industrial facilities. Properties developed under previous operating requirements could require electrical upgrades or other infrastructure improvements to accommodate tenants implementing advanced technologies. As a result, the competitiveness of industrial real estate portfolios may increasingly depend on their ability to adapt to changing operational needs rather than simply offering additional square footage.
Looking toward 2030, Mexico’s industrial growth potential will depend on its ability to translate geographic advantages into reliable operating conditions. Hagg’s remarks indicate that nearshoring continues to represent an opportunity for the country, but that industrial competitiveness requires addressing infrastructure limitations that cannot be resolved through real estate development alone.
The modernization of electricity distribution networks, strategic planning for water availability, and adaptation of industrial properties to energy-intensive technologies will be essential considerations as companies evaluate future investments. In this context, Mexico’s challenge is not simply to attract new manufacturing and logistics projects, but to ensure that the infrastructure required to support them is available when businesses are ready to expand.