

Ethereum co-founder Vitalik Buterin has challenged one of ETH’s most familiar investment arguments: that transaction-fee burns give the token a reliable valuation floor. In a November 8 post, he argued that Ethereum should prioritize ETH as a store of value, even if burning fees never comes close to offsetting new issuance. Here’s why that matters for Ethereum’s economics, and where the new argument still leaves ETH holders with questions. You guys can use Binance refcode for 40% discount on trading fee.
Ethereum’s Fee Burn Is No Longer Carrying the Valuation Argument
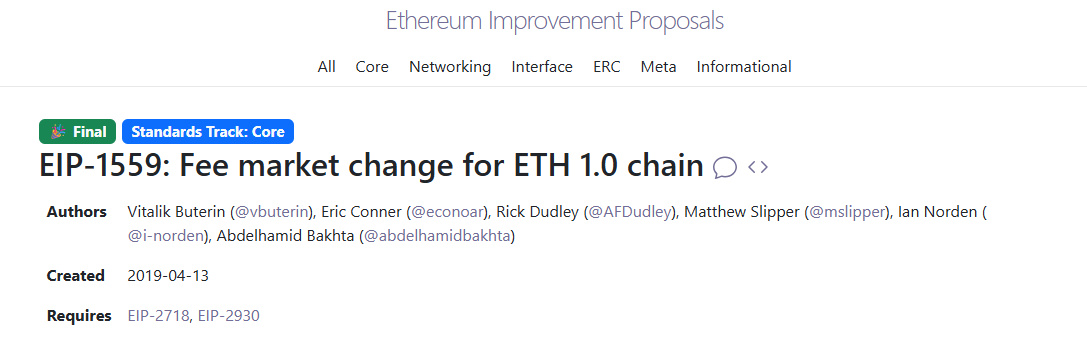
Ethereum’s EIP-1559 destroys the base fee paid on transactions rather than passing it to validators. When activity is sufficiently expensive, burns can exceed new issuance, shrinking supply. That helped popularize the idea of ETH as “ultrasound money” after the mechanism went live in 2021.
But a possible supply contraction is not the same as a reliable source of value. According to ethsupply.fyi, Ethereum issued about 890,446 ETH and destroyed 21,153 ETH between January 1 and November 10, 2026, based on its November 10, 01:23 UTC snapshot. Total destruction offset only about 2.4% of issuance. That figure includes more than EIP-1559 base fees, so fee burning alone accounts for even less.
In his November 8 thread, Buterin said holders should not be disappointed if fee burning stays below 10% of the level needed to offset issuance indefinitely. He wasn’t proposing to remove EIP-1559. He was questioning why its burn should define the value of ETH in the first place.
A $270 Billion ETH Valuation Exposes the Problem With the Old Model
Buterin illustrated the weakness of a burn-based valuation with a simplified present-value calculation: market capitalization equals annual fees burned divided by a discount rate. Under that model, $1 billion in dependable annual burns at a 4% rate could support a theoretical valuation of $25 billion.
Apply the same assumptions to the approximately $270 billion ETH market capitalization Buterin cited, and the implied annual burn rises to 10.8billion(270 billion × 4%). This isn’t a price target. It illustrates the recurring burn implied by a simplified valuation model.
The underlying problem is that Ethereum’s biggest historical fee spikes were often funded by crypto speculation. When speculation crashes, willingness to pay high fees falls too, undermining the supposed valuation floor. Nor is a token burn identical to a cash dividend: its benefit depends on supply, demand, the price at which fees are paid and the durability of activity.
Buterin sees tokenized real-world assets as a better source of demand from outside crypto. Yet mature financial activity may generate relatively modest, predictable fees rather than the dramatic gas-price spikes that once made the burn look impressive.
Chasing Higher Fees Could Make Ethereum Less Useful
Maximizing Ethereum’s fee burn would also create the wrong incentives, Buterin argues. High transaction costs can increase the amount of ETH destroyed, but those same costs make the network less accessible to people and businesses using it. A protocol designed to extract more fees from every user could undermine the very adoption that makes Ethereum valuable.
His corporate analogy sharpens the trade-off. A network expected to justify a roughly $270 billion valuation through revenue-like burn might be pressured to spend heavily on development and actively steer itself toward whatever businesses generate the most fees. Buterin estimated that corporate-style research spending could demand around 700,000 ETH a year in protocol funding, with consequences for validator rewards and governance.
That tension has already surfaced in Ethereum’s issuance debate. Memeburn previously examined EIP-8363’s proposed burn of staking rewards, which was later pulled from the Hegotá upgrade after concerns about validator incentives and concentration. And Ethereum’s lower-cost layer-2 strategy highlights the same contradiction: cheaper transactions can improve usability even when they produce less immediate burn revenue on the base chain.
Building a useful network and maximizing the value of destroyed transaction fees are different goals, even when they occasionally reinforce each other.
Vitalik’s Store-of-Value Case Starts With Survival
Buterin’s alternative rests on what he calls CROPS: censorship and capture resistance, open source, privacy and security. For someone storing assets over many years, the ability to retain control, transact without arbitrary exclusion and depend on a resilient network may matter more than any month’s token-burn figure.
He points to easier self-custody, privacy tools, lighter nodes and protection against future cryptographic threats. The Ethereum Foundation’s September protocol priorities similarly emphasize censorship resistance and post-quantum security. These are engineering priorities, not guarantees that ETH will hold its market price. A technically dependable blockchain can still have a volatile token.
The store-of-value argument also differs from Bitcoin’s scarcity-first narrative. Ethereum has changing issuance, staking incentives and an evolving application layer. Buterin’s case is that its durability and usefulness as neutral financial infrastructure could make ETH worth holding, rather than that supply alone makes it scarce.
Ethereum Must Still Prove That Network Adoption Benefits ETH
Memeburn’s reading is that Vitalik has made a stronger case for protecting Ethereum’s usefulness than for assigning a specific value to ETH. The roughly 2.4% burn-to-issuance ratio makes it difficult to treat deflation as the foundation of the token’s current economics, while the $10.8 billion calculation shows the scale of dependable burns needed to explain a $270 billion valuation under the simplified model. Neither result disproves a store-of-value thesis, but both force investors to separate network success from token value capture.
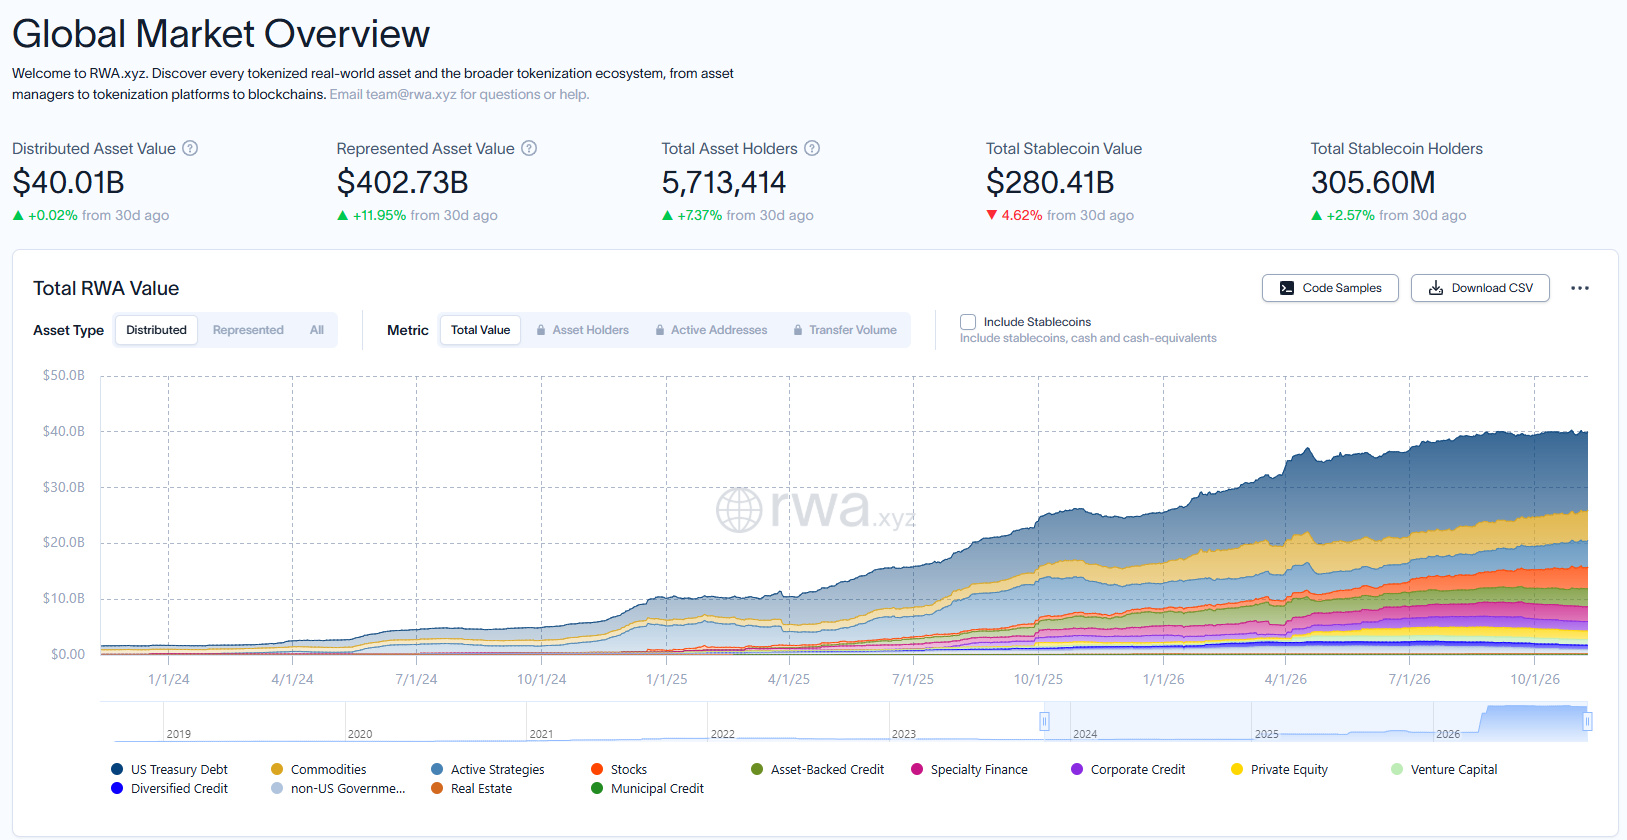
There is real evidence of financial demand. RWA.xyz listed roughly $15.1 billion in distributed real-world assets on Ethereum in its November 10 network table. Memeburn’s earlier analysis of Ethereum’s RWA ecosystem explained why institutions may value the chain as a place to issue and hold assets. Yet $1 billion in tokenized securities does not create $1 billion in demand for ETH. Custodians can manage assets while holding relatively little ETH, and the fees generated may be small compared with the underlying asset value.
That leaves the most important test unresolved. If ETH becomes more widely used as collateral, for staking and as a reserve asset inside on-chain finance, its economic role could grow even with limited burns. If activity expands mainly in ways that require little ETH ownership, however, Ethereum’s adoption may run ahead of the token’s investment case. The next useful numbers to follow are therefore not just fees destroyed, but sustained ETH demand for collateral, security and long-term holdings.