Inflation is still biting, with October’s producer prices running hot and interest rates looking sticky, so pricing power suddenly matters a lot more than hype. That backdrop can reward companies that handle rising costs or punish those that cannot, and the gap between the two can widen quickly. This article walks through three US energy sector stocks exposed to this inflation story and explains why each might deserve a closer look right now.
The three stocks below are just a starting sample, and the full screening process surfaced 10 more US energy players with equally compelling inflation and pricing power stories that are not covered here.
If you want to identify which of these larger producers, refiners and service groups best matches your own risk and income goals, head straight into the US Energy Sector Stocks screener to analyze the full list and focus on your highest conviction setups.
Riley Exploration Permian slots neatly into this US energy screen as a pure-play Permian producer, and the analyst consensus Narrative on Simply Wall St highlights how its development choices and infrastructure build-out could turn that commodity exposure into something more resilient for shareholders.
“The shift in development activity toward New Mexico, combined with infrastructure projects such as expanded saltwater disposal and oil gathering systems, is expected to support higher oil volumes over several years and feed through to revenue.”
What really matters now is how one pressure on Riley Exploration Permian’s cost base interacts with that growth push and ultimately shapes margins.
Riley Exploration Permian is an independent oil and gas producer focused on Permian Basin acreage in Texas and New Mexico. This makes it a direct fit for the US Energy Sector Stocks screener’s emphasis on sizeable, liquid upstream operators. The business generated about US$578 million from oil and gas exploration and production activities, and with a market cap near US$977 million it sits in the smaller side of the listed U.S. energy group but still clears the screen’s thresholds for scale and tradability.
That margin story is only half the picture, and the full narrative for Riley Exploration Permian shows how capital choices, decline curves and payout priorities could be quietly reshaping Riley Exploration Permian’s risk profile.
NYSEAM:REPX Revenue & Expenses Breakdown as at Nov 2026
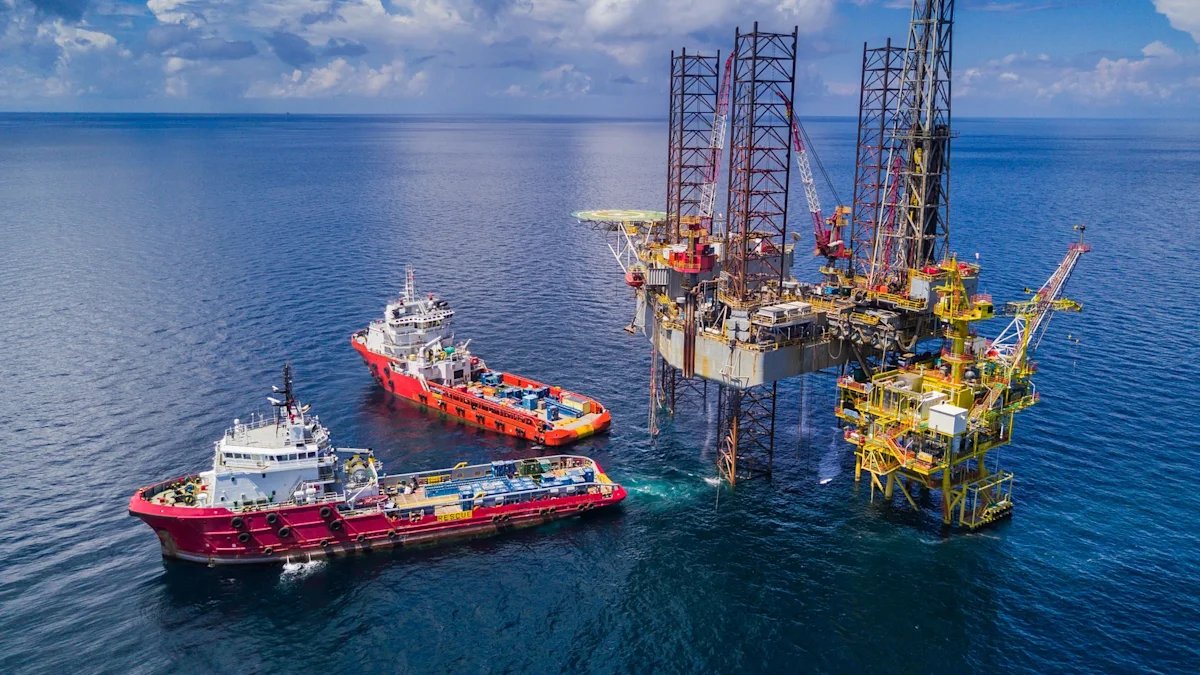
Noble Corporation plugs into this US Energy Sector Stocks screen as a pure-play offshore driller, giving investors exposure to how stronger oil prices can filter into higher rig dayrates and better utilization. The analyst consensus Narrative on Simply Wall St points to why contracted work and pricing power now matter so much.
“A backlog of about US$6.8 billion as of late July 2026, with roughly US$1.0 billion scheduled to convert to revenue in the rest of 2026 and US$2.3 billion in 2027, plus multi year extensions such as the Noble Courage contract through 2030, provides line of sight on contracted activity that can support revenue stability.”
The real swing factor is how one less visible cost and execution pressure interacts with that backlog when investors judge future cash generation.
That hidden pressure is exactly what the full narrative for Noble unpacks, separating short term rig noise from longer term cash flow potential and highlighting where Noble’s story could be accelerating.
NYSE:NE Revenue & Expenses Breakdown as at Nov 2026
CVR Energy fits neatly into this US Energy Sector Stocks theme as a U.S. refiner and fuel producer whose fortunes are closely tied to refined product pricing, and the analyst consensus Narrative on Simply Wall St focuses on how cost pressures interact with that earnings power.
“Escalating RFS compliance costs, including recent net RIN expense levels of $143 million in one quarter and $216 million in the next, are set to remain a large structural burden that can continue to compress net margins and free cash flow even if headline crack spreads stay supportive.”
What really moves the needle for CVR Energy now is how one shifting cost burden intersects with refined product margins that many investors are watching closely.
That shifting burden is exactly what the full narrative for CVR Energy unpacks, separating structural headwinds from potential margin recovery and flagging where CVR Energy’s story could be quietly accelerating.
NYSE:CVI Revenue & Expenses Breakdown as at Nov 2026
Seeking Alternatives Before Momentum Flies
Fresh ideas move first. Once momentum builds and prices start flying, the best setups often get caught quickly. Scan these under the radar lists before the crowd, and consider acting while they remain less noticed.
This article is general in nature and was produced with the assistance of AI automation, based on data and analysis from Simply Wall St. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.