



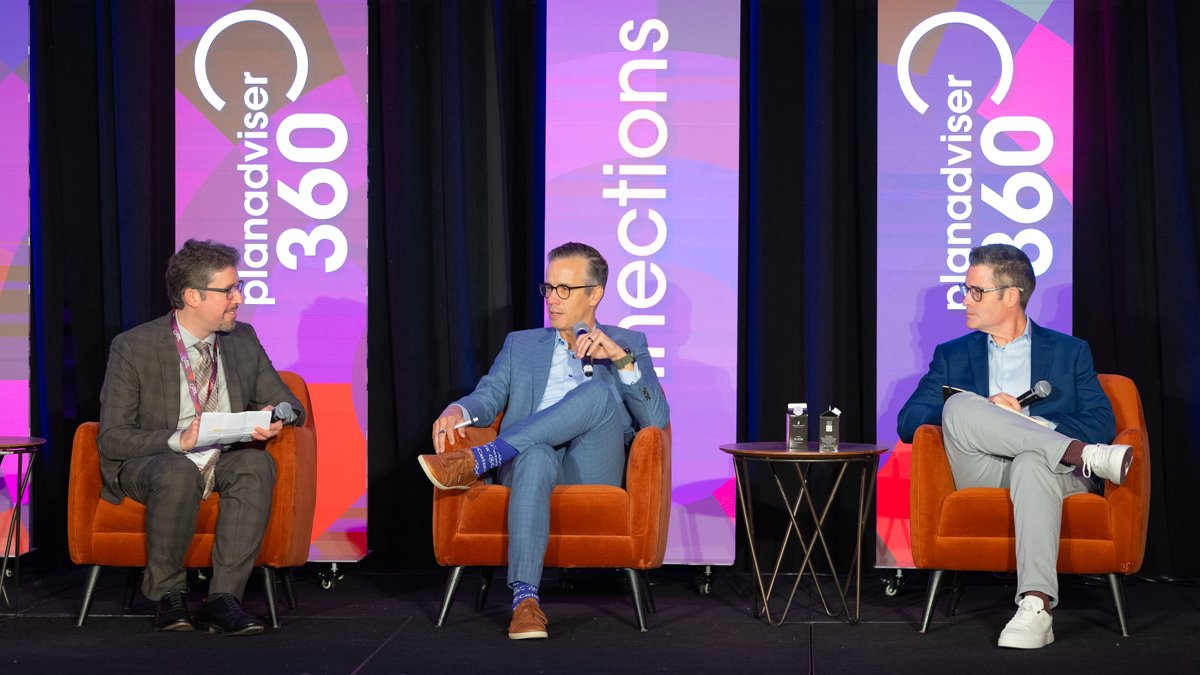
Retirement plan advisers looking to position their firms for long-term growth should focus on scalability, talent development, participant engagement and strategic use of artificial intelligence, according to experts at a Tuesday session, “Future-Proof Your Practice,” at the 2026 PLANADVISER 360 Conference in Orlando, Florida.
Jon Anderson, head of workplace and retirement at Cetera Financial Group, and Chad Wilson, market principal, wealth services at OneDigital Retirement + Wealth, stressed that firms need to reduce their reliance on individual advisers to remain competitive amid changing technology and client expectations.
“You can’t have a single point of failure in a practice, if you’re going to build something that’s going to last beyond you, that’s going to be able to be scalable, that you’re going to be able to grow,” Wilson said.
At OneDigital, Wilson said his team restructured client service models to have multiple professionals involved in every client relationship. Rather than having one lead adviser manage all aspects of a plan, Wilson said clients engage with “a senior consult, a supporting consultant, an education specialist and an investment specialist.” That approach, he said, helps firms withstand employee departures while creating a more scalable business model.
Anderson said many of the industry’s fastest-growing firms share a similar focus on removing operational friction.
“One thing that was a resounding item that all of the fastest-growing advisers did, one is they all had retirement plan business,” Anderson said. “But two, they tried to remove as much friction from their business as possible, which means creating as many repeatable processes and as much scale as possible.”
According to Anderson, firms that standardize workflows and outsource functions, where appropriate, allow advisers to focus on higher-value activities such as business development and client relationships. He said these characteristics also increase a firm’s attractiveness to potential acquirers because the revenue stream is easier to replicate.
Recruiting the Next Generation
Considering the advisory industry’s aging workforce and the need to develop a next generation of advisers, Wilson said some of his strongest employees entered the profession through internship programs designed to provide meaningful exposure to the business. Rather than assigning interns administrative tasks, his firm treats internships as extended trial runs for future employment.
“This is an audition,” Wilson said. “You’re going to be joined at the hip with a senior adviser. You’re going to get exposure to wealth management, investment consulting, retirement plan consulting.”
At the conclusion of successful internships, students may receive full-time employment offers, creating a pipeline of young talent for the organization.
Anderson said younger professionals are often attracted less by a particular industry than by opportunities to solve meaningful problems. Retirement plan advisory firms can appeal to those interests by involving new hires in areas such as participant engagement, data analytics and workplace financial wellness initiatives.
“If you pose it to them as a problem to solve—‘Look, our industry is trying to solve how to engage participants better at scale’—that’s something they get really excited about and will do the grunt work and the grind in order to solve for that,” Anderson said.
In turn, firms that successfully recruit younger professionals can also be appealing to private equity firms making acquisitions, according to Anderson.
“PE firms, they want to see continuity, they want to see succession,” he said. “They want to see that pipeline of talent within your organization.”
Tackling AI as a Team
As artificial intelligence disrupts the advisory business, Wilson said that firms should begin identifying which functions truly require human expertise and which can be automated. Routine activities such as preparing committee materials may eventually become largely technology driven, allowing advisers to spend more time with clients.
He said the human touch will become more crucial as tech companies are likely to devise programs to handle increasing aspects of advisers’ analytical and administrative work.
“That 10-person [tech] company is coming for us and they’re going to do what we do at half the price and steal our clients if we don’t build our relationships,” Wilson said.
Anderson similarly encouraged advisers to embrace AI as a productivity tool rather than view it solely as a threat.
“If we can create a team of individuals that learn how to use the technology in AI incredibly well, think about what we can accomplish as a small team,” Anderson said. “The key in the future world is [to] focus on where you can add human value and if it can be repeatable, if it can be scaled. If technology can fill that gap, then you need to try to embrace that as fast as possible.”