This article appeared in the Nov 11, 2026 issue of the monthly print edition. Subscribe now.
Malaysia’s property market continues to paint a picture of resilience, as the most recent National Property Information Centre (Napic) 1H2026 Property Market Report confirms the residential sector remains stable with overall prices inching upwards by 0.9% (although transaction volume softened by 7.7%), while the industrial sector saw transaction value increase 3.8% y-o-y to RM14.78 billion.
In the commercial sector, a modest growth of 0.9% was recorded in the first half of the year.
However, elevated levels of unsold inventory and subdued demand continued to weigh on overall performance, with softening occupancy rates emerging as a key underlying challenge.
Interestingly, a breakdown of data actually pointed to improved occupancy trends in most key economic regions — hovering around a healthy 70-75% benchmark. The outlier was the ongoing slow performance of Johor’s large commercial market, contributing to a subdued overall national performance.
Napic’s 1H2026 report noted that Johor’s commercial market continued to lag with a 66.3% average occupancy rate (up a slight 0.6 percentage points from the previous year), but this was being outpaced by increased supply, which had expanded by another 1% — primarily driven by the ongoing completion of purpose-built offices and shopping complexes.
Notably, supply has outpaced demand in the southern state for more than a decade now, yet the report highlighted Johor as being among the states with the largest incoming supply of commercial space this year. It begs the question: Why is the buffet of commercial space continuing to grow in a region that does not seem to have an appetite for it?
The answer lies in “potential” and “promise”, say market professionals. Massive government infrastructure investments, the Rapid Transit System (RTS) linkage with Singapore, and a booming industrial sector are seen as ingredients to a successful economic recipe, and developers are bullishly positioning themselves to benefit.
“We believe both the RTS Link and JS-SEZ (Johor–Singapore Special Economic Zone) have contributed to positive market sentiment. The RTS Link is expected to benefit retail and commercial activities, particularly in Johor Bahru city centre (JBCC), while the JS-SEZ drives broader economic growth and demand for commercial and industrial properties,” JLL Malaysia head of research & advisory Yulia Nikulicheva tells EdgeProp.
“Improved cross-border connectivity will further strengthen investor confidence and support workforce mobility. However, positive market sentiment does not necessarily translate into immediate demand, but depends on occupier demand and supply absorption,” she says.
Most market watchers agree there is also cause for caution. After decades of relentless development, questions are beginning to emerge over how much of Johor’s existing stock of vacant commercial space is now ageing, and how much of it will still meet the needs and expectations of modern occupiers when the state’s long-promised economic potential is finally realised.
The purpose-built problem
Perhaps unsurprisingly, the two commercial property segments that account for the largest share of incoming supply are also those grappling with the weakest occupancy rates.
However, the key difference between shopping complexes and purpose-built offices is that retail users tend to be more flexible in what they need, whereas office occupiers are increasingly demanding very specific building standards.
This makes it easier for malls to refresh to meet updated demand than offices, thereby making unoccupied purpose-built offices the greater challenge that Johor faces.
The numbers confirm that assessment, with a 55.9% occupancy rate for purpose-built offices in the private sector (Chart 1) reflecting a larger problem than the 75.4% occupancy rate shopping complexes in Johor currently face, with 90% being the typical healthy benchmark for retail centres.
The Napic 1H2026 report also made a point to identify Johor’s office woes, stating that of the approximately 10.52 million sq ft of floor space available, some 4.72 million sq ft remained unoccupied, which was almost half.
Amidst this market pressure, total supply increased by 0.30 million sq ft y-o-y. Cumulatively, these numbers combined to make it the most distressed office market in the country.
The root cause can be traced to the state’s structural oversupply legacy. Johor went through a severe oversupply cycle in 2014–2016, and it has been playing catch-up since, fluctuating between improved periods and dips. However, the current situation also coincides with a challenging office environment overall, where evolving modern corporate needs are reshaping demand.
Challenging market shifts compound the issue
In general, the office market has become increasingly polarised. Performance has depended largely on building quality, connectivity and how well assets meet changing occupier needs.
Leasing activity has also grown more selective, and the gap has widened across submarkets and building grades.
Looking at the Klang Valley experience, for example, newer high-specification buildings have continued to attract most occupier demand. The strongest interest has gone to assets with green certifications, integrated amenities and good accessibility. Occupiers are also gradually moving away from traditional office precincts towards integrated mixed-use developments, reflecting changing workplace requirements.
Older buildings, by contrast, have come under growing pressure to retain tenants as occupiers relocate to better-quality space. Landlords of older stock are increasingly relying on refurbishment, asset enhancement and repositioning to stay competitive.
Demand has been driven mainly by work-place optimisation and selective expansion, particularly among technology firms, business services providers, financial institutions and flexible workspace operators.
In Johor, policy and infrastructure catalysts such as the JS-SEZ framework and the RTS Link have helped reposition parts of the market as cost-effective, well-connected corporate locations within the cross-border growth corridor.
However, this has also seen the rise of segment differentiation, and confidence is not uniform. While Grade A offices close to RTS-linked focal points have strong prospects, shrinking interest in generic older office towers in suburban locations may result in prolonged overhang issues.
Knight Frank Malaysia’s Real Estate Highlights 1H2026, for example, points out that average Grade A office occupancy recorded an increase of 4.9% from 2H2025, significantly outpacing Grade B office spaces which registered a marginal growth of 0.2%.
The report, which examined rental performance, also stated that Grade A offices in key nodes within JB “command higher asking rents of between RM4 and RM6 psf, [while] the average rental rates across JB held steady between RM3.10 and RM 3.80 psf. This variance is primarily due to the high composition of Grade B inventory in the market, which continues to moderate overall rental averages”.
Rents actually achieved are lower than the asking figures suggest. Stamped tenancy agreements captured by EdgeProp EPIQ show that office leases signed in JB’s better-established towers between January 2024 and June 2026 closed at a median of RM3.20–RM3.50 psf, at or below the bottom of the Grade A asking range.
Leases at Menara Komtar recorded a median of RM3.50 psf across 11 agreements, the JB City Square office tower RM3.30 psf across 18, and Menara Landmark RM3.20 psf across nine.
Older stock sat well below that level. Leases at Menara Zurich closed at a median of RM2.50 psf, even as space in the building is advertised on EdgeProp at RM3.80 psf. The three leases recorded at City Plaza on Jalan Tebrau ranged about RM1.00–RM2.05 psf, in line with the RM1.86 psf median for office lots elsewhere in the state, much of it in shop-office buildings (Chart 2).
Old towers, new owners
While leasing remains slow, sales records show that JB’s older office stock is changing hands in large blocks. EPIQ records five block or whole-building office purchases in the city centre between January 2025 and March 2026, worth about RM122 million in total (Chart 3).
The largest of these was City Plaza on Jalan Tebrau. In 2017, Singapore-listed Pavillon Holdings Ltd agreed to buy 107 lots in the 28-storey complex and adjoining land for RM52 million, against an independent valuation of RM70 million. EPIQ shows no corresponding transfer, suggesting the deal did not complete. In December 2025, however, 82 units changed hands on the same day, most at exactly RM120 psf, for about RM31 million, followed by another 16 units for about RM13 million in March 2026.

In 2014, units in the building changed hands at a median of about RM380 psf.
Smaller buildings under single ownerships near the RTS terminus have fetched far higher prices. A 12-storey office block on Jalan Tenteram in the Bukit Meldrum area (roughly 800m from RTS terminus) sold for RM30 million in November 2025, about RM540 psf, five times the RM5.98 million it fetched in 2012. A four-storey office building on Jalan Bukit Timbalan (about 1km from RTS terminus) changed hands for RM13.8 million, about RM520 psf, in May 2025.
Menara Landmark is the one strata tower where prices have risen: a full floor sold at RM650 psf in January 2025, up from about RM300 psf for a unit in early 2023 (Chart 4).
The pattern mirrors the polarisation seen in the Klang Valley, with one difference specific to Johor. Buyers are paying for single ownership and proximity to the RTS. Fragmented strata towers, which cannot be repositioned until their units are brought under one owner, are trading at prices that reflect that difficulty.
Why supply keeps expanding despite surplus
The RTS Link connecting Woodlands in Singapore to JB and the JS-SEZ are widely seen as game-changers to the landscape in the southern state. As previously mentioned, developers in Johor are essentially betting on future demand, building stock now to capture tenants and investors once these projects fully materialise.
Once projects are launched and financing is secured, developers rarely halt construction, even if demand softens. This is due to developer momentum and commitments. Even if occupancy trends weaken, the financing and construction schedules already in place push projects forward to avoid sunk costs or contractual penalties.
Many Johor projects were planned years earlier, tied to cross-border positioning with Singapore, so completions keep flowing regardless of current occupancy.
This ties to prevailing industry concerns about the fragmentation of Johor’s property market, with multiple developers competing to secure land and deliver projects ahead of demand. This creates a risky “race to build” scenario, where supply growth is driven by competition rather than actual absorption.
In the purpose-built office context, the rush to build in strategic locations within anticipated economic hotspots has unfortunately led to plenty of empty spaces that are simply waiting for the “right time”. Furthermore, this adds to earlier-built spaces, from previous anticipated boom cycles, within corridors that have still not quite lived up to their billing.
“We note that developers have been more actively eyeing commercial developments in Johor, especially around RTS locations, but a lack of clarity on the JS-SEZ blueprint is slowing down Singaporean business expansion into Malaysia,” says Nikulicheva.
“Additionally, developers are waiting for the RTS link to be launched, as Singaporean businesses require a clear vision of how they may relocate part or all of their businesses into Malaysia. Any business considering this strategy would also need to take into account other operational costs of relocation, such as travel time and cost as well as talent retention,” she says.
A significant share of Johor’s incoming office supply is also concentrated in the Iskandar Puteri–Medini corridor, home to the Medini central business district (CBD), which Iskandar Investment Bhd identifies as the flagship development zone of Iskandar Malaysia.
Medini North, in particular, is envisioned to be a new-generation business district catering to a regional cross-border workforce, and accommodating a strong global business services (GBS) and multinational corporation (MNC) presence.
Grade A premium offices in the area have been registering improvements of late, buoyed by increased MNC participation. While Napic figures only focus on a state or regional level, market consultants active in Medini, such as Olive Tree Property Consultants, say Grade A offices in the vicinity could soon see occupancy of up to 70%–85%, based on growing interest.
This is in contrast to Medini’s weak performance in its early years, which sat at 10%– 30% occupancy, according to the Medini & Forest City Corridor Commercial Property Guide (Singapore). More recently, occupancy has risen alongside the growing momentum of the JS-SEZ plan.
Unlike the city centre, Medini’s purpose-built offices were not sold off as strata units. The towers are held by a small number of landlords, among them Medini Pulse Sdn Bhd, Medini Development Sdn Bhd, UEM Group Bhd and Iskandar Education Enterprise Sdn Bhd, so transaction records say little about the area.
EPIQ records no office unit sales in Medini and just one office building transaction in the wider Nusajaya, the RM31 million sale of Bangunan Seri Medini in May 2020. As a result, absorption is largely driven by leasing activity.
Stamped tenancy records in EPIQ show a cluster of commitments at Menara IIB (formerly Medini 9) within October 2025–January 2026, with most leases commencing in 2026. Tenants include Reazon Malaysia Sdn Bhd, Aegis BPO Malaysia Sdn Bhd and Compact Building Materials Sdn Bhd, alongside new leases at Teega Office Tower and EduCity (Table 1).


The rents achieved show that Medini’s newer stock is not commanding a premium. Grade A space at Menara IIB is being let at about RM3.00–RM3.20 psf, and space at Teega and EduCity at about RM3.50 psf, broadly in line with established towers in JBCC (Chart 4).
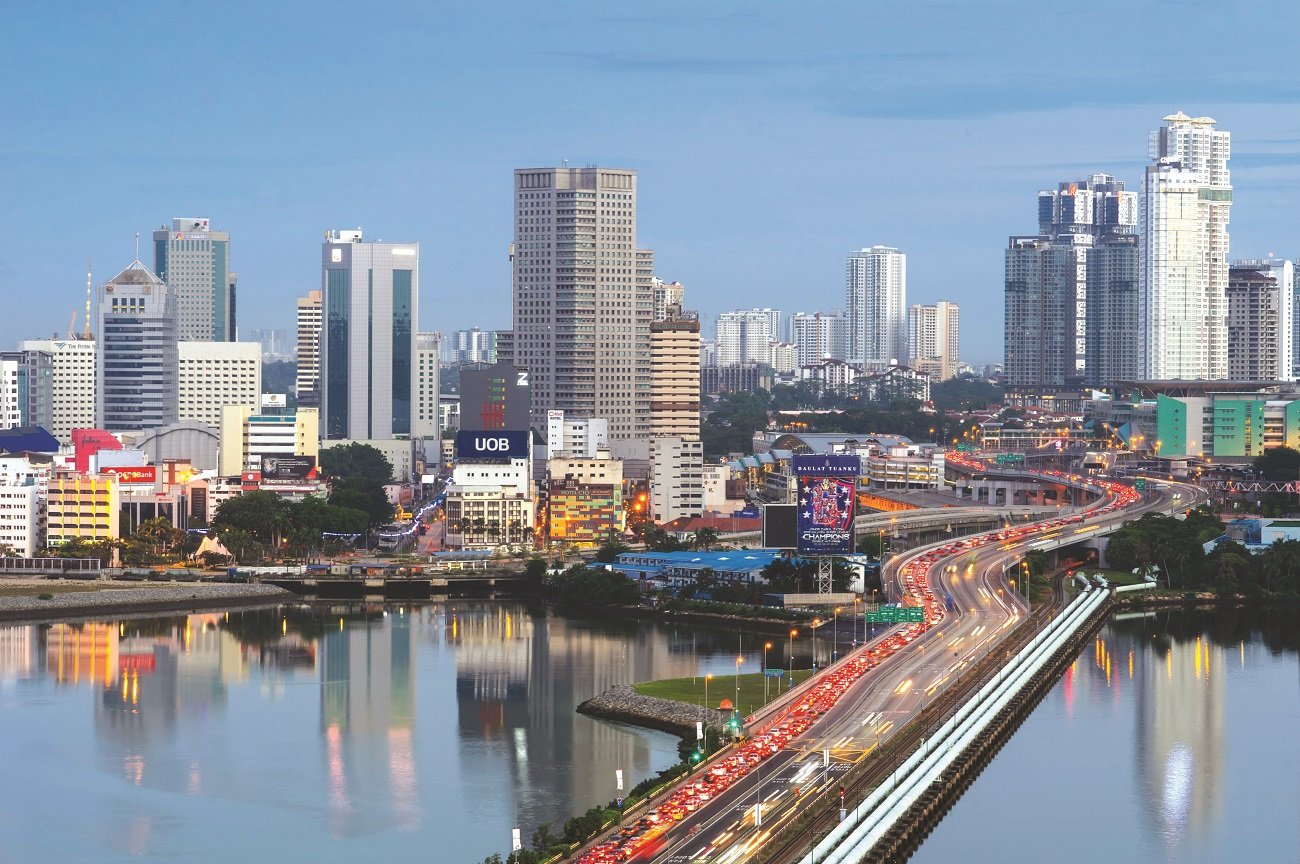
Similarly, JBCC continues to be the dominant established office node, supporting government institutions as well as local corporations with a traditional city-based workforce.
Grade A office stock in the city is considerably tighter than the wider market, with analysts indicating a vacancy of roughly 15%–20%.

This bodes well for a market that is expecting a boost following the imminent completion of the RTS Link, which many market professionals hope will translate into enhanced take-up of not just Grade A office stock, but also spill over into other vacant office spaces within impacted vicinities.
Naturally, the areas poised to benefit most from the RTS Link are JBCC, particularly the Bukit Chagar precinct surrounding the RTS station, followed by Medini and Iskandar Puteri, which stand to gain from enhanced cross-border connectivity and rising demand from companies seeking a lower-cost base (compared with Singapore) within the JS-SEZ.
Other important commercial office clusters in Johor include EduCity, Puteri Harbour, Kota Iskandar and the Southern Industrial and Logistics Cluster, each strategically designated to serve distinct economic functions and business needs (Table 2).
Better days for JB offices on the horizon?
There is, however, some relief in sight for Johor’s troubled office market.
The RTS Link is now scheduled to begin operations in 1Q2027 after completing final testing and regulatory approvals. With a five-minute journey between Bukit Chagar and Woodlands North and capacity for up to 10,000 passengers per hour in each direction, industry players expect leasing momentum to build from 2027 onwards as companies reassess operating costs, workforce deployment and location strategies, while the JS-SEZ begins converting investment commitments into business activity.
The JS-SEZ secured RM88.83 billion in approved investments between January 2025 and June 2026, according to figures cited by Economy Minister Akmal Nasrullah Mohd Nasir at the Johor-Singapore Cooperation Ministerial Committee (JSCMC) meeting in Singapore on Nov 2. The market is also expected to see early “selective demand” for properties near JB Sentral and CIQ (customs, immigration and quarantine) hubs, which will likely benefit from quicker absorption due to proximity, convenience and demand from business travellers.
Highlighting the transformation RTS will bring to Johor, Malaysia International Chamber of Commerce and Industry (MICCI) Southern Region chairman Lee Ting Kiat told the press recently that cross-border businesses currently have to “plan around unpredictable travel times when meeting customers, moving people or travelling across the Causeway”.
“The RTS changes that. Businesses can plan with greater certainty, and that gives investors and businesses more confidence to grow,” he said.
JLL’s Nikulicheva also believes the RTS will stimulate growth in office space requirements.
“Some Singapore-based companies could be incentivised by the JS-SEZ policy to move their offices to Johor. This does not mean they will relocate all their employees to Malaysia, but rather relocate the business and hire local staff, while management could remain based in Singapore. With the RTS link, this strategy would be much easier to implement,” she says.
For office occupiers, this means Johor can become a more viable location for regional back-office operations, shared services centres, professional services firms, and technology and support teams serving Singapore clients.
MICCI also expects greater cross-border certainty to translate into improved labour mobility, enhanced facilitation of business collaboration and greater organisational confidence when planning operations and making investment decisions across the Johor-Singapore corridor. In practical terms, companies based in Johor offices will have a larger talent pool that includes workers who can commute regularly between two countries.
While the RTS is expected to provide a much-needed demand catalyst for office, retail and mixed-use commercial developments, it should not be viewed as a panacea for Johor’s broader office market challenges.
Overall, occupier demand will still depend on the success of JS-SEZ as a long-term alternative business hub for international corporations, availability of skilled labour, last-mile connectivity within JB, as well as the quality and competitiveness of office stock.
Several business groups have noted that the RTS Link and JS-SEZ, while important catalysts, must be complemented by wider economic and planning measures to convert commuter flows into lasting commercial demand.
Addressing existing vacancies will also be crucial, particularly among older office buildings that lack the specifications sought by modern occupiers. As demand shifts towards ESG (environmental, social and governance)-compliant, hybrid-ready and service-oriented workplaces, ageing stock faces growing repositioning challenges.


In response, calls for adaptive reuse have gained momentum. Consultants including Olive Tree and Knight Frank have argued that underutilised office spaces may require alternative uses to improve building utilisation.
Olive Tree expands further by suggesting obsolete offices could potentially be converted into co-working hubs, student accommodation, wellness and healthcare facilities, event spaces or lifestyle-oriented commercial uses.
This view is significant because it signals that parts of the market are beginning to acknowledge that some older offices may never achieve strong traditional office occupancy again. The block purchase of units at City Plaza suggests the process has already begun, with a buyer assembling a fragmented strata tower that would otherwise be difficult to reposition.
Ultimately, infrastructure development, coupled with innovative and well-executed asset repositioning, is likely to be the key catalyst required to effectively reshape Johor’s commercial property market.
……….
EdgeProp monthly brings you data, insights and solutions for an evolving market. Subscribe now for your free copy!